

Banking and Credit
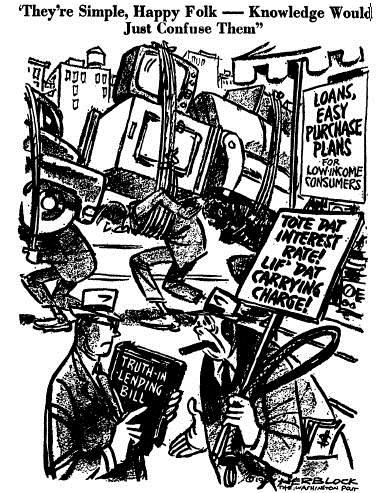
Since the Great Depression, Congress has passed a series of laws to preserve stability in the banking and credit industries, protect consumers from unfair and deceptive practices and make affordable credit available to middle class and low-income families and small businesses. Beginning in the 1980s, the deregulation of financial institutions has fed speculative booms and devastating busts. Privatization of low-cost government credit for student loans and mortgages and weaker consumer protections has driven up the cost of credit and put consumers at risk.
Commentary
Information is power… and that’s the problem
Why #OccupyWallStreet?
Cry Wolf Quotes
“As an industry leader, Chase does not engage in several practices -- universal default, two-cycle billing and increasing a rate based on a change in a credit score -- addressed by the bill, but we believe the legislation as passed today has the potential of increasing overall costs to consumers, reducing access to credit, and reducing or eliminating low-rate options for consumers.”
[The bill], while well-intentioned, will increase the cost of credit for consumers and small businesses across the country, result in less access to credit for consumers and businesses alike, and may further roil the securities markets -- all at a time when our economy can least afford it.
The roots of this crisis go back to the Carter administration. That was when government officials, egged on by left-wing activists, began accusing mortgage lenders of racism and "redlining" because urban blacks were being denied mortgages at a higher rate than suburban whites. The pressure to make more loans to minorities (read: to borrowers with weak credit histories) became relentless. Congress passed the Community Reinvestment Act, empowering regulators to punish banks that failed to "meet the credit needs" of "low-income, minority, and distressed neighborhoods." Lenders responded by loosening their underwriting standards and making increasingly shoddy loans.
The Community Reinvestment Act (CRA) did the same thing with traditional banks. It encouraged banks to serve two masters -- their bottom line and the so-called common good… By pressuring banks to serve poor borrowers and poor regions of the country, politicians could push for increases in home ownership and urban development without having to commit budgetary dollars. Another political free lunch.
Related Laws and Rules
Evidence
-
Banking Lobby's Warnings About CARD Act Disproven
What happened after credit card reform bill passed Congress in 2009 (it worked).
-
The Successes of the CARD Act
The Consumer Financial Protection Bureau describes exactly what the act did and what the effects were one year later.
Backgrounders & Briefs
A Timeline of the CARD Act
An interactive timeline of credit card reform.
Resources
The National Community Reinvestment Coalition works against unfair lending and banking practices, particularly those targeted towards low and middle income families.
