

Banking and Credit
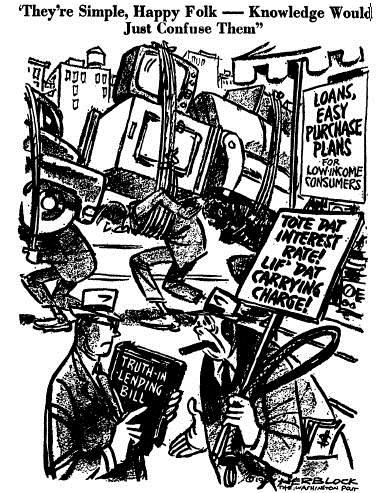
Since the Great Depression, Congress has passed a series of laws to preserve stability in the banking and credit industries, protect consumers from unfair and deceptive practices and make affordable credit available to middle class and low-income families and small businesses. Beginning in the 1980s, the deregulation of financial institutions has fed speculative booms and devastating busts. Privatization of low-cost government credit for student loans and mortgages and weaker consumer protections has driven up the cost of credit and put consumers at risk.
Commentary
Information is power… and that’s the problem
Why #OccupyWallStreet?
Cry Wolf Quotes
There is no evidence of significant discrimination in mortgage lending.
The CRA, by encouraging loosening underwriting standards, may have contributed to the massive increase in foreclosure rates.
The important question, however, is not the default rates on the mortgages made under the CRA. Whatever those rates might be, they were not sufficient to cause a worldwide financial crisis. Once these standards were relaxed--particularly allowing loan-to-value ratios higher than the 80 percent that had previously been the norm--they spread rapidly to the prime market and to subprime markets where loans were made by lenders other than insured banks.
It is simply wrong-headed policy…[Federal and state banking regulations] require or aggressively nudge banks into subsidizing parts of the community [The proposals] would only aggravate the problem.
Related Laws and Rules
Evidence
-
Banking Lobby's Warnings About CARD Act Disproven
What happened after credit card reform bill passed Congress in 2009 (it worked).
-
The Successes of the CARD Act
The Consumer Financial Protection Bureau describes exactly what the act did and what the effects were one year later.
Backgrounders & Briefs
A Timeline of the CARD Act
An interactive timeline of credit card reform.
Resources
The National Community Reinvestment Coalition works against unfair lending and banking practices, particularly those targeted towards low and middle income families.
